
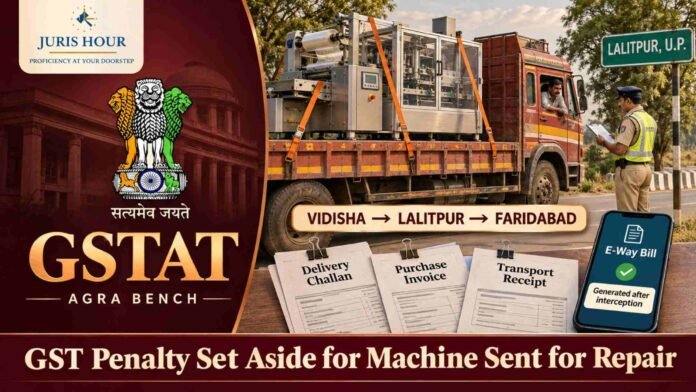
The Goods and Services Tax Appellate Tribunal (GSTAT), Agra Bench, has dismissed an appeal by the Uttar Pradesh State Tax Department and upheld the cancellation of a penalty under Section 129(3) of the Central and Uttar Pradesh GST Acts. The dispute arose after a defective machine was sent from Madhya Pradesh to Haryana for repair without an e-way bill at the start of its journey.
The bench of Ajeet Singh (Judicial Member) and Vivek Kumar (Technical Member) found that the shipment was genuinely for repair and that the department had produced no reliable evidence of an intention to evade tax.
Buy Now: All 200+ GSTAT Judgements Till November 2026 | Comprehensive E-Magazine
The bench treated the failure to generate the e-way bill before dispatch as a technical breach.
The assessee is based in Ganj Basoda in Madhya Pradesh’s Vidisha district, purchased the machine from an Ahmedabad supplier on 24 February 2023. After the machine developed a technical defect, the firm sent it to Faridabad, Haryana, for repair. The consignment was accompanied by the original purchase invoice, a transport receipt or bilty dated 7 July 2023, and a delivery challan issued under Rule 55 of the CGST Rules.
A mobile squad intercepted the vehicle in Lalitpur, Uttar Pradesh, on 8 July 2023. The driver produced all three documents during the inspection. The taxpayer generated and furnished the e-way bill that day, before the proper officer issued a show-cause notice under Section 129(3).
The taxpayer explained that it had mistakenly understood the e-way bill requirement to apply only to movements involving a taxable sale. The proper officer rejected the explanation and imposed a penalty for non-compliance with Rule 138. The first appellate authority set aside the penalty on 29 November 2023, prompting the department to appeal to GSTAT under Section 112(1).
The Tribunal held that sending the machine across state borders solely for repair and return did not amount to a supply of goods under Section 7. It observed that the repairer’s charges are separately taxable as a supply of services. Rule 55(1)(c) permits the use of a delivery challan for goods transported for reasons other than supply.
The bench recognised that Rule 138 generally requires an e-way bill before movement when the consignment value exceeds ₹50,000, including where goods move for reasons other than supply. The issue before the Tribunal was whether the omission justified the Section 129(3) penalty on the facts of this case.
The Tribunal found that the original purchase invoice established ownership, while the delivery challan and transport receipt supported the stated purpose of the movement and showed that the machine had been handed over to a carrier.
The bench also treated the generation of the e-way bill before issuance of the show-cause notice as evidence of the taxpayer’s bona fides.
The bench drew on the Supreme Court’s decision in Assistant Commissioner, State Tax v. Satyam Shivam Papers Pvt. Ltd., (2022) 14 SCC 157, and referred to Allahabad High Court decisions on transit penalties. Given the documents produced at interception, the genuine repair movement and the absence of evidence of tax evasion, GSTAT upheld the first appellate order setting aside the penalty.
Membership Required to Access Case Details & Order Copy
To view the complete Case Details and Download Order Copy, you must have an active membership. Please subscribe to continue.
Read More: SCN Alone Can’t Justify Departmental Appeal Below Rs. 20 Lakh on Grounds of Recurrence: GSTAT

