
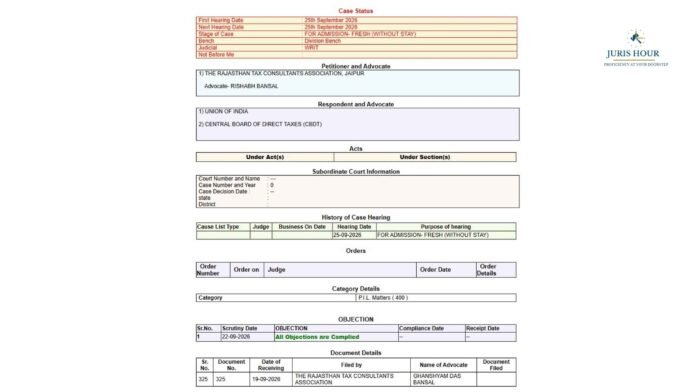
The issue concerning extension of the tax audit report filing deadline has reached the Rajasthan High Court, with the Rajasthan Tax Consultants Association, Jaipur approaching the Court through a writ petition against the Union of India and the Central Board of Direct Taxes (CBDT).
According to the case-status details available on the Rajasthan High Court portal, the matter has been registered before the Division Bench and is listed for “For Admission – Fresh (Without Stay)”. The matter is scheduled to come up for hearing on 25 September 2026.
Buy Now: Think Before You Pay Cash: 50+ Landmark Rulings on Section 40A(3) Of The Income Tax Act, 1961
The development assumes significance for tax professionals and taxpayers who are awaiting clarity on the deadline for completion and filing of tax audit-related compliances.
Rajasthan Tax Consultants Association Files Writ Petition
The writ petition has been filed by the Rajasthan Tax Consultants Association, Jaipur, with Advocate Rishabh Bansalshown as the advocate for the petitioner in the Court status.
The respondents listed in the case are:
- Union of India
- Central Board of Direct Taxes (CBDT)
The case has been categorised under P.I.L. Matters (400) and is presently before a Division Bench of the Rajasthan High Court.
The Court record shows the matter at the stage of admission – fresh (without stay). This means that the matter is presently at the initial stage of judicial consideration and the available status does not indicate that any interim stay or final relief has been granted by the Court at this stage.
Notices Served on CBDT and Income Tax Department
As stated in the update shared by the Rajasthan Tax Consultants Association, notices have been served on the CBDT/Income Tax Department in connection with the writ petition.
The association has described the development as acceptance of its writ petition by the High Court and has informed the tax fraternity that the matter will be taken up on 25 September 2026.
The Court’s case-status page, meanwhile, records the matter for 25 September 2026 under the purpose of hearing as “FOR ADMISSION- FRESH (WITHOUT STAY)”.
Hearing Fixed for September 25
The case-history section of the Court status records the following:
| Particular | Details |
| Petitioner | Rajasthan Tax Consultants Association, Jaipur |
| Respondents | Union of India & CBDT |
| Bench | Division Bench |
| Case Type | Writ |
| Stage | Admission – Fresh (Without Stay) |
| Category | P.I.L. Matters (400) |
| First Hearing Date | 25 September 2026 |
| Next Hearing Date | 25 September 2026 |
| Advocate for Petitioner | Rishabh Bansal |
| Scrutiny Date | 22 September 2026 |
| Scrutiny Status | All objections complied |
| Document Received | 19 September 2026 |
The Court record also shows that the scrutiny objections were marked as complied with, indicating that the procedural objections raised at the scrutiny stage had been addressed.
What Is the Tax Audit Extension Dispute?
The petition concerns the demand for an extension of the tax audit-related deadline. The issue is particularly relevant to chartered accountants, tax consultants, businesses and other taxpayers required to comply with tax-audit provisions.
However, the presently available case-status information does not set out the detailed grounds of challenge, the specific extension period sought, or the substantive submissions made by the association. Those aspects would have to be examined from the writ petition and subsequent Court orders.
Accordingly, the filing of the writ petition should not at this stage be treated as a direction by the Rajasthan High Court extending the tax-audit deadline.
No Stay or Extension Granted Yet
An important aspect of the present status is the designation:
“FOR ADMISSION – FRESH (WITHOUT STAY)”
Therefore, while the matter has been listed before the Division Bench and the association has stated that notices have been served upon the CBDT, the available status does not show that the Court has, as of now, granted an interim stay or ordered an extension of the tax-audit deadline.
The hearing on September 25 could therefore be significant for determining how the Court proceeds with the petition at the admission stage and whether any interim directions are sought or considered.
Why the September 25 Hearing Is Significant
The tax-audit compliance process involves coordination between taxpayers and tax professionals within prescribed statutory and procedural timelines. Any request for additional time can therefore have implications for professionals handling large numbers of tax-audit assignments as well as taxpayers whose returns and related compliances are connected with the audit process.
The Rajasthan petition brings the issue before the High Court at a time when the compliance deadline is a matter of immediate concern for the tax-professional community.
The proceedings on September 25 will provide greater clarity on:
- whether the writ petition is admitted;
- the response of the Union of India and CBDT;
- the precise relief sought by the petitioner;
- whether the Court considers any interim relief;
- and whether any direction is issued concerning the tax-audit deadline.
Case Status as of September 23, 2026
The latest status shared shows that the petition has cleared the scrutiny stage, with the objection status recorded as “All Objections are Complied.” The matter is listed before the Rajasthan High Court’s Division Bench for 25 September 2026.
For the moment, therefore, the development represents a judicial challenge seeking consideration of the tax-audit extension issue, rather than an extension already granted by the Court.
The tax-professional community will be closely watching the proceedings scheduled for 25 September 2026, when the Rajasthan High Court is expected to take up the matter at the admission stage.
JurisHour Update: Rajasthan Tax Consultants Association’s writ petition concerning extension of the tax-audit deadline is listed before the Rajasthan High Court Division Bench on September 25, 2026. The case status records “Admission – Fresh (Without Stay),” while the association has stated that notices have been served on CBDT/Income Tax authorities.
Read More: 6% CENVAT Liability Not Applicable on Bagasse-Based Electricity Sold to MSEDCL: CESTAT

