
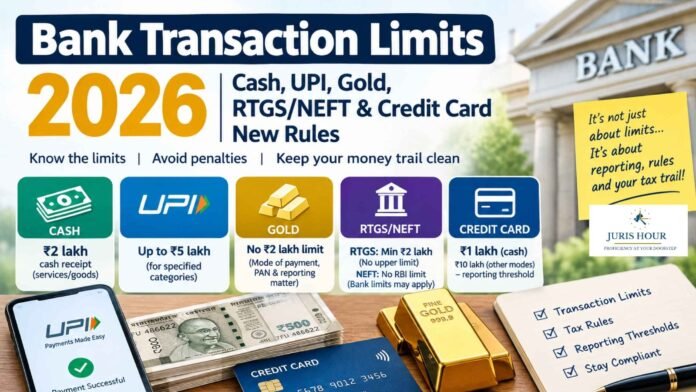
Banking transactions in India are increasingly being monitored through a combination of banking records, PAN-linked reporting, Statement of Financial Transactions (SFT), digital-payment systems and tax information. However, there is a common misconception that every large transaction is prohibited once it crosses a particular limit.
In reality, the rules are different for cash transactions, UPI payments, bank transfers, credit-card payments, gold purchases and cash withdrawals. Some limits are actual legal restrictions, while others are only thresholds at which banks or other reporting entities are required to report transactions to the tax authorities.
Buy Now: E-Magazine: 1000+ Landmark GST Judgments (2017–2026)
The financial year 2026-27 also brings an important background change because the Income-tax Act, 2025 is now relevant to the tax framework, while several established transaction-control principles continue in substance.
Here is a detailed guide to the major transaction limits that individuals, businesses and professionals should know in 2026.
1. Is There a General Limit on How Much Money Can Be Transferred From One Bank Account to Another?
There is no single universal ₹10 lakh, ₹20 lakh or ₹50 lakh ceiling applicable to all bank transfers.
The permitted amount depends on the payment channel used, the bank’s internal risk controls and, in some cases, the nature of the transaction.
For example, RBI’s RTGS framework does not prescribe an upper ceiling. RTGS has a minimum transaction amount of ₹2 lakh, while there is no maximum amount prescribed by RBI.
Similarly, RBI does not impose a general maximum amount for NEFT transfers. Individual banks, however, may prescribe limits for customers based on their products, channels, security controls and risk policies.
Therefore, a large bank transfer is not automatically illegal merely because it exceeds ₹10 lakh or ₹50 lakh.
The more important question is whether the transaction is genuine, properly documented and consistent with the taxpayer’s financial profile and disclosed income.
2. RTGS Transaction Limit in 2026
RTGS is principally intended for high-value transactions.
RTGS limit
- Minimum amount: ₹2 lakh
- RBI-prescribed maximum: No upper ceiling
- Available: 24x7x365
- Actual customer limits: May depend on the bank and the channel used
Thus, a person can transfer substantially more than ₹10 lakh through RTGS where the bank permits it.
The absence of an upper RBI ceiling should not, however, be confused with the absence of tax scrutiny. A high-value transaction can still be visible through banking records and other financial-information reporting mechanisms.
3. NEFT Transaction Limit in 2026
NEFT is another major electronic fund-transfer mechanism.
RBI does not prescribe a maximum amount for NEFT transactions. Banks may nevertheless impose their own limits.
This means that the frequently circulated statement that “NEFT is limited to ₹10 lakh” is not a universal RBI rule.
The applicable limit may instead depend on:
- Internet banking limits;
- Mobile banking limits;
- Branch-initiated transactions;
- Customer category;
- Account type;
- Bank-specific risk controls; and
- Additional authentication requirements.
For high-value transfers, customers should therefore check the applicable limit with their bank rather than relying on a general figure circulating online.
4. UPI Transaction Limit in 2026
UPI is different from RTGS and NEFT because NPCI prescribes transaction limits depending upon the category of transaction, while banks may also apply customer-specific limits.
The standard UPI limit for many ordinary transactions has traditionally been around ₹1 lakh per transaction, although limits can vary according to the category.
NPCI has also increased the per-transaction limits for specified categories.
For example, NPCI’s 2025 circular increased the per-transaction UPI limit for specified merchant categories aligned with tax payments to ₹5 lakh.
This means that the statement “UPI limit is ₹5 lakh” should not be treated as a blanket rule applicable to every UPI payment.
The applicable limit depends upon the transaction category, merchant, bank and UPI implementation.
Important point
A taxpayer should distinguish between:
UPI transaction limit
and
income-tax reporting of transactions.
A UPI payment of ₹5 lakh does not automatically mean that the amount is taxable. Similarly, splitting a large transaction into several UPI payments does not change the underlying tax character of the transaction.
5. Can ₹5 Lakh or More Be Paid Through UPI?
Yes, in categories for which NPCI has permitted the enhanced limit, subject to the participating bank and merchant supporting the facility.
NPCI has specifically provided higher per-transaction limits for selected categories, including certain tax payments.
However, a customer should not assume that every UPI ID can send ₹5 lakh merely because the general UPI framework contains a ₹5 lakh category limit.
Banks can impose lower limits.
6. Cash Deposit in a Savings Account: ₹10 Lakh Reporting Threshold
One of the most important figures taxpayers should know is ₹10 lakh.
Cash deposits aggregating to ₹10 lakh or more in a financial year in one or more accounts, other than current accounts and specified time deposits, fall within the prescribed financial-transaction reporting framework.
This does not mean that depositing ₹10 lakh in cash is prohibited.
It means that the transaction can become reportable to the tax authorities.
Consequently, a person depositing substantial cash should be able to explain:
- Source of cash;
- Nature of income;
- Business receipts, if any;
- Withdrawals and redeposits;
- Cash book and books of account;
- Supporting invoices;
- Sale documents; and
- Corresponding entries in the income-tax return.
The crucial distinction is:
₹10 lakh is primarily a reporting threshold, not a blanket prohibition on cash deposits.
7. Cash Deposits in Current Accounts: ₹50 Lakh Reporting Threshold
For current accounts, the prescribed SFT framework covers aggregate cash deposits or cash withdrawals of ₹50 lakh or more during a financial year.
Again, this is not a general prohibition on depositing or withdrawing ₹50 lakh.
It is a threshold for financial-information reporting.
Businesses handling significant cash should therefore maintain proper books, cash registers, invoices, receipts and banking records.
A legitimate business can have cash transactions exceeding the reporting threshold. The concern arises where the cash movement cannot be reconciled with the books, turnover or disclosed sources.
8. Cash Withdrawal From Bank: Is There a Limit?
There is no universal rule saying that an individual can never withdraw more than ₹10 lakh or ₹20 lakh in cash.
However, tax consequences and reporting requirements can arise.
The major provision is the cash-withdrawal TDS mechanism.
Under the existing framework, where specified cash withdrawals cross the prescribed thresholds, tax may be deducted at source.
For a person who has filed income-tax returns for the relevant preceding years, TDS under Section 194N applies at 2% on cash withdrawals exceeding ₹1 crore in the applicable circumstances.
For a person who has not filed returns for the prescribed preceding years, the thresholds are substantially lower: TDS can apply at 2% on cash withdrawals exceeding ₹20 lakh and at 5% on withdrawals exceeding ₹1 crore.
Therefore, taxpayers should not confuse:
cash withdrawal limit
with
cash withdrawal TDS threshold.
A TDS threshold does not necessarily mean that the bank account holder is prohibited from withdrawing the money.
9. Cash Payment for Goods or Services: ₹2 Lakh Rule
One of the most important restrictions for individuals and businesses relates to cash receipts.
The tax framework restricts receipt of ₹2 lakh or more in cash in specified circumstances.
Broadly, the restriction applies where a person receives ₹2 lakh or more:
- from a person in a day;
- in respect of a single transaction; or
- in respect of transactions relating to one event or occasion,
subject to the statutory exceptions.
Therefore, simply dividing a ₹3 lakh transaction into several cash instalments may not necessarily avoid the restriction if the payments relate to the same transaction or event.
This is particularly relevant for:
- Sale of goods;
- Sale of services;
- Property-related transactions;
- Jewellery transactions;
- Business receipts;
- Large personal purchases; and
- Event-related payments.
The rule should therefore not be interpreted as “₹1,99,999 cash is always safe.”
The nature and aggregation of the transactions must be examined.
10. Cash Payment for Business Expenses: ₹10,000 Rule
For business expenditure, the tax law contains restrictions on deduction where expenditure is paid in cash beyond the prescribed threshold.
The familiar rule under the earlier Income-tax Act framework restricted deduction of certain business expenditure where payment to a person otherwise than through prescribed banking/electronic modes exceeded ₹10,000 in a day.
A higher threshold applies in specified cases involving payments to transport operators.
The important practical point is that this is primarily a deductibility rule, not necessarily a prohibition on physically making every such payment.
For businesses, therefore, a cash payment above the prescribed threshold can create a problem because the expenditure may not be allowed as a deduction while computing taxable business income, subject to statutory exceptions.
11. Cash Loans and Deposits: ₹20,000 Rule
Tax law also restricts acceptance and repayment of loans and deposits in cash beyond the prescribed threshold.
The familiar threshold is ₹20,000.
Broadly, the restriction covers:
- Taking loans in cash;
- Accepting specified deposits in cash; and
- Repaying specified loans/deposits in cash.
The restrictions are subject to statutory exceptions for specified persons and circumstances.
This is especially important for businesses, partnerships, companies and individuals dealing with large private loans.
A common mistake is to assume that because a person has sufficient cash, a ₹50,000 or ₹1 lakh cash loan can simply be recorded in the books.
The tax law can treat such transactions differently from ordinary cash receipts.
12. Gold Purchase Rules in 2026
Gold and jewellery transactions are another area where cash-payment rules and PAN requirements become important.
There is no general rule saying that a person cannot purchase gold worth more than ₹2 lakh.
The important issue is the mode of payment and reporting requirements.
A jewellery purchase can be paid through:
- Account-payee cheque;
- Bank transfer;
- UPI where supported;
- Card/payment mechanisms; or
- Other permitted banking channels.
Cash payment for a high-value purchase can trigger restrictions under the income-tax framework.
Further, PAN requirements apply to specified high-value purchases and transactions.
Therefore, the popular statement that “you cannot buy gold above ₹2 lakh” is inaccurate.
The issue is principally about cash payment, PAN/documentation and reporting, rather than an absolute ceiling on the value of gold that an individual can purchase.
13. Does Buying Gold Above ₹2 Lakh Require PAN?
PAN requirements apply to specified transactions above prescribed thresholds.
For purchases or sales of goods/services, the tax rules prescribe PAN quoting requirements once the transaction crosses the applicable threshold.
Jewellery dealers may therefore request:
- PAN;
- Aadhaar or other identity documents;
- Address details;
- Invoice details;
- Payment information; and
- Other KYC documentation.
For a large gold purchase, taxpayers should preserve the complete invoice and payment trail.
A bank transfer from the purchaser’s account to the jeweller’s account provides a substantially clearer transaction trail than a large cash payment.
14. Credit Card Payment: ₹1 Lakh Cash and ₹10 Lakh Other Modes
Credit-card transactions have their own financial-information reporting thresholds.
Under the SFT framework, payments against one or more credit cards during a financial year become reportable at prescribed thresholds:
- ₹1 lakh or more where payment is made in cash, or
- ₹10 lakh or more through other modes.
These are reporting thresholds.
They do not mean that a person is prohibited from paying more than ₹10 lakh towards credit-card bills through banking channels.
The credit-card issuer or relevant reporting entity can report qualifying transactions to the tax authorities.
Therefore, taxpayers making substantial credit-card payments should ensure that their sources of funds are properly documented.
15. Does a ₹10 Lakh Credit Card Bill Mean Income Tax Will Be Charged?
No.
Payment of a credit-card bill is not automatically taxable income.
However, if a person’s financial records show:
- High-value credit-card expenditure;
- Low declared income;
- Large unexplained bank deposits;
- Significant cash deposits;
- Investments inconsistent with disclosed income; or
- Payments for assets without an identifiable source,
the transaction trail can become relevant during tax verification or scrutiny.
The important issue is not merely the amount of expenditure but whether the taxpayer can explain the source.
16. Large Bank Transfers and Income-Tax Scrutiny
There is no general tax rule stating:
“If you transfer more than ₹10 lakh, income tax will send a notice.”
That is an oversimplification.
A large bank transfer may represent:
- Sale proceeds;
- Business receipts;
- Loan;
- Gift;
- Investment;
- Property transaction;
- Transfer between own accounts;
- Redemption of investment;
- Capital contribution;
- Family transfer; or
- A completely legitimate financial transaction.
The tax significance depends on the nature and source of the money.
For example, transferring ₹20 lakh from one bank account to another account belonging to the same person is fundamentally different from receiving ₹20 lakh as unexplained cash from a third party.
17. Transfer Between Own Bank Accounts
There is generally no income-tax restriction merely because a taxpayer transfers a large amount from one bank account to another account belonging to the same taxpayer.
For example:
Account A → Account B: ₹25 lakh
does not automatically constitute taxable income.
However, taxpayers should retain adequate documentation where the transfer involves:
- Different banks;
- Joint accounts;
- Business and personal accounts;
- Proprietorship accounts;
- Family members; or
- Multiple entities.
The purpose of the transfer should be identifiable from the bank statement and accounting records.
18. IMPS Transaction Limits
IMPS is another instant-payment mechanism.
Unlike RTGS and NEFT, IMPS limits can depend significantly on the bank and channel.
Many banks prescribe customer-level limits around the ₹5 lakh range, but this should not be treated as a universal RBI ceiling for every customer and every bank.
The exact limit should therefore be checked with the concerned bank.
19. Bank Drafts, Pay Orders and Similar Instruments
Cash purchases of bank drafts, pay orders and certain prepaid instruments are also subject to financial-information reporting and PAN requirements.
Transactions aggregating to ₹10 lakh or more in a financial year fall within specified reporting categories.
For certain cash payments, PAN quoting requirements can arise at much lower levels.
This is another reason why high-value transactions should preferably be conducted through traceable banking channels.
20. Fixed Deposits and Other Time Deposits
Time deposits are also subject to reporting requirements.
The SFT framework provides for reporting of specified time deposits aggregating to ₹10 lakh or more in a financial year, subject to the applicable rules and exclusions.
This does not mean that a person cannot create an FD exceeding ₹10 lakh.
Rather, the transaction can become reportable.
A taxpayer investing ₹20 lakh in a fixed deposit should therefore ensure that the source of the investment is properly reflected in their financial records.
21. ₹10 Lakh Is Not a Universal “Bank Account Limit”
This is perhaps the most important clarification for taxpayers in 2026.
There is no universal rule saying:
“You cannot deposit more than ₹10 lakh.”
Nor is there a universal rule saying:
“Any transaction above ₹10 lakh is illegal.”
Different ₹10 lakh thresholds appear in different provisions for different purposes.
For example:
| Transaction | Important threshold | What it generally means |
| Cash deposit in savings/other specified account | ₹10 lakh/year | SFT reporting threshold |
| Time deposits | ₹10 lakh/year | SFT reporting threshold |
| Credit-card payment through non-cash modes | ₹10 lakh/year | SFT reporting threshold |
| Cash deposit/withdrawal in current account | ₹50 lakh/year | SFT reporting threshold |
| Cash payment for certain goods/services | ₹2 lakh | Restriction/reporting implications |
| Cash loan/deposit | ₹20,000 | Restriction under tax law |
| Business cash expenditure | ₹10,000/day | Deduction restriction, subject to exceptions |
| RTGS | ₹2 lakh minimum | No RBI upper ceiling |
| NEFT | No RBI upper ceiling | Bank/channel limits may apply |
| UPI | Depends on category | NPCI/bank limits; higher limits for specified categories |
| Credit-card payment in cash | ₹1 lakh/year | SFT reporting threshold |
22. Does Splitting Transactions Avoid the Rules?
This is an important misconception.
Suppose a person is required to pay ₹3 lakh for a single transaction and attempts to make:
- ₹1 lakh today;
- ₹1 lakh tomorrow; and
- ₹1 lakh the day after.
The fact that each individual payment is below ₹2 lakh does not automatically make the entire arrangement compliant.
Several tax provisions specifically look at:
- A single day;
- A single transaction;
- Transactions relating to one event or occasion; or
- Aggregate transactions during a financial year.
Similarly, splitting cash deposits into multiple bank accounts may not eliminate reporting requirements where the applicable rule requires aggregation of accounts belonging to the same person.
23. What Happens When a Transaction Is Reported?
A reported transaction is not automatically a tax offence.
Financial institutions and other reporting entities furnish specified information to the tax authorities.
Such information may subsequently appear in the taxpayer’s tax-information records and can be compared with:
- Income-tax returns;
- GST returns;
- TDS/TCS data;
- PAN;
- Bank information;
- Property transactions;
- Securities transactions;
- Credit-card payments;
- Cash deposits;
- Investment transactions; and
- Other available financial information.
If the transaction is genuine and properly explained, reporting by itself does not mean that additional tax is payable.
24. Large Transactions Should Be Supported by a Clear Money Trail
In 2026, taxpayers should increasingly focus not merely on staying below an arbitrary threshold but on maintaining a proper source-of-funds trail.
For a large transaction, the taxpayer should ideally be able to establish:
Where did the money come from?
Why was it received or paid?
Who was the counterparty?
Was it recorded in the books?
Was it reflected in the income-tax return, where required?
Is there an invoice, agreement, bank statement or other supporting document?
These questions become particularly important for cash-intensive businesses and high-value personal transactions.
25. Key Rules Taxpayers Should Remember in 2026
The most important practical points are:
Cash
Cash receipts and cash payments are subject to several restrictions. The ₹2 lakh cash-receipt rule is particularly important for businesses and high-value transactions.
UPI
UPI does not have one universal limit applicable to every transaction. Category-specific limits exist, including enhanced limits for certain payments.
RTGS
RTGS has a minimum ₹2 lakh transaction size and no RBI-prescribed maximum ceiling.
NEFT
RBI does not impose a general maximum transaction amount, although individual banks can prescribe limits.
Cash deposits
₹10 lakh is an important annual SFT reporting threshold for cash deposits in specified non-current accounts.
Current accounts
₹50 lakh is an important annual reporting threshold for aggregate cash deposits or withdrawals in current accounts.
Credit cards
₹1 lakh cash payments and ₹10 lakh non-cash payments towards credit-card bills are important SFT thresholds.
Gold
There is no general ₹2 lakh ceiling on buying gold. The key issues are the mode of payment, cash restrictions, PAN/KYC requirements and reporting.
Cash loans
₹20,000 is an important threshold for restrictions on specified cash loans and deposits.
Cash business expenditure
₹10,000 per day is the familiar threshold beyond which specified cash business expenditure can face deduction restrictions, subject to exceptions.
Cash withdrawals
Cash withdrawal TDS provisions can become relevant at high annual withdrawal levels, particularly ₹1 crore for specified taxpayers and lower thresholds for persons who have not filed returns for the relevant preceding years.
Conclusion
The major banking and transaction rules in 2026 are not simply about placing a maximum limit on how much money an individual can move.
The regulatory framework works through three different mechanisms:
1. Transaction limits — such as the limits prescribed for UPI or the ₹2 lakh minimum for RTGS.
2. Tax restrictions — such as restrictions on specified cash receipts, cash loans and cash business expenditure.
3. Reporting thresholds — such as ₹10 lakh cash deposits, ₹50 lakh current-account cash transactions and specified credit-card payment thresholds.
Understanding this distinction is critical.
A transaction crossing a reporting threshold is not automatically illegal or taxable. At the same time, a taxpayer should not assume that keeping each individual transaction below a reporting threshold will automatically avoid scrutiny where the underlying transactions are connected.
For individuals and businesses, the safest approach for high-value transactions in 2026 is to maintain a clear banking trail, use appropriate non-cash modes wherever practical, preserve invoices and agreements, and ensure that significant transactions are properly reflected in books and tax filings wherever required.
The key lesson is simple: there is no single “bank transaction limit” in India. The applicable rule depends on the type of transaction, the payment mode, the annual aggregate and the purpose for which the money is received or paid.

