
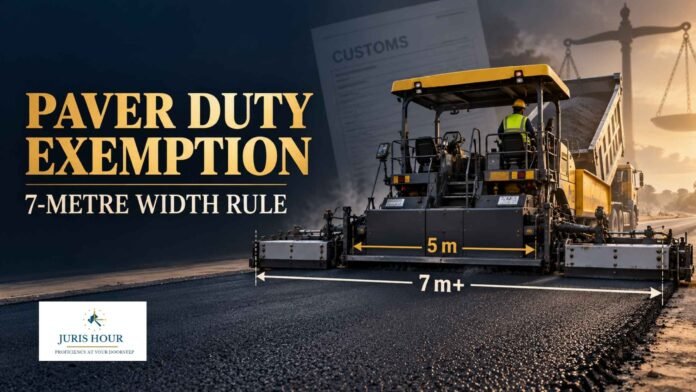
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Chennai upheld the denial of duty exemption on two imported road pavers and the use of the extended limitation period. It removed the personal penalty on the company’s director because his role in the misdeclaration was not established.
The bench of P. Dinesha (Judicial Member) and M. Ajit Kumar (Technical Member) has observed that a road paver whose paving width reaches nine metres only after bolt-on extensions are added does not qualify for a customs duty exemption intended for electronic paver finishers capable of laying bituminous pavement of seven metres and above.
Buy Now: E-Way Bill Judgements From 2020–2026 [Includes Orders of GSTAT]
The appellant/assessee company and its director, Prem Singh, against a 2018 order of the Commissioner of Customs, Chennai-III. The Tribunal dismissed the company’s appeal but partly allowed the director’s appeal by deleting the personal penalty imposed on him.
The appellant/assessee imported two electronic sensor pavers in 2012, declaring a combined assessable value of ₹2,98,48,740. It claimed the benefit of Notification No. 12/2012-Cus., under which specified equipment required for road construction could be imported at a nil rate of customs duty, subject to the notification’s conditions.
The relevant entry covered an “electronic paver finisher (with sensor device) for laying bituminous pavement 7 m size and above.” The assessee maintained that the machines could pave up to nine metres wide when fitted with the bolt-on extensions supplied with them.
Customs authorities disputed the claim. Their investigation found that the machines could pave only up to approximately five metres without the additional extensions. A show cause notice issued in June 2017 proposed recovery of duty with interest and penalties. The Commissioner confirmed the demand and imposed a separate penalty on the director.
The assessee argued that it had ordered pavers for laying pavement up to nine metres wide and that the necessary extensions were supplied along with the machines. According to the company, the notification required the ability to lay pavement at least seven metres wide; it did not require a paver to achieve that width without extensions.
The company also challenged the extended limitation period. It said the purchase and import documents had been made available to Customs when the goods were assessed and cleared, and denied suppressing or misdeclaring any material fact.
The department argued that the declared description did not disclose the machines’ built-in paving width or explain that external additions were needed to reach the width claimed for exemption.
The Bench examined the import documents and the findings of a physical verification conducted in February 2017. The verification recorded a basic screed width of 2.25 metres, extendable to five metres, and found no additional member connected to the machine at the time.
The Tribunal noted the company’s own acknowledgment that, without the additional bolt-on extensions, a machine could lay pavement only up to five metres wide. It was also unconvinced by the company’s reliance on the proforma invoice: the Bench said it did not find in that document the description of expanding accessories that the company had asserted was present.
Holding that the condition in the exemption notification had to be met by the imported machine itself, the Tribunal rejected the argument that fitting bolt-on extensions brought a five-metre paver within the entry for pavers of seven metres and above. It also noted that the description in the Bill of Entry did not specifically state the machine’s paving capability. The Bench consequently upheld the denial of exemption and the department’s invocation of the extended limitation period.
The Tribunal reached a different conclusion on the penalty imposed on Prem Singh. It found no specific allegation identifying his role in the misdeclaration and no adequate discussion in the Commissioner’s order of an act or omission by him that had caused it. The personal penalty was therefore unsustainable and was deleted.
Membership Required to Access Case Details & Order Copy
To view the complete Case Details and Download Order Copy, you must have an active membership. Please subscribe to continue.

