
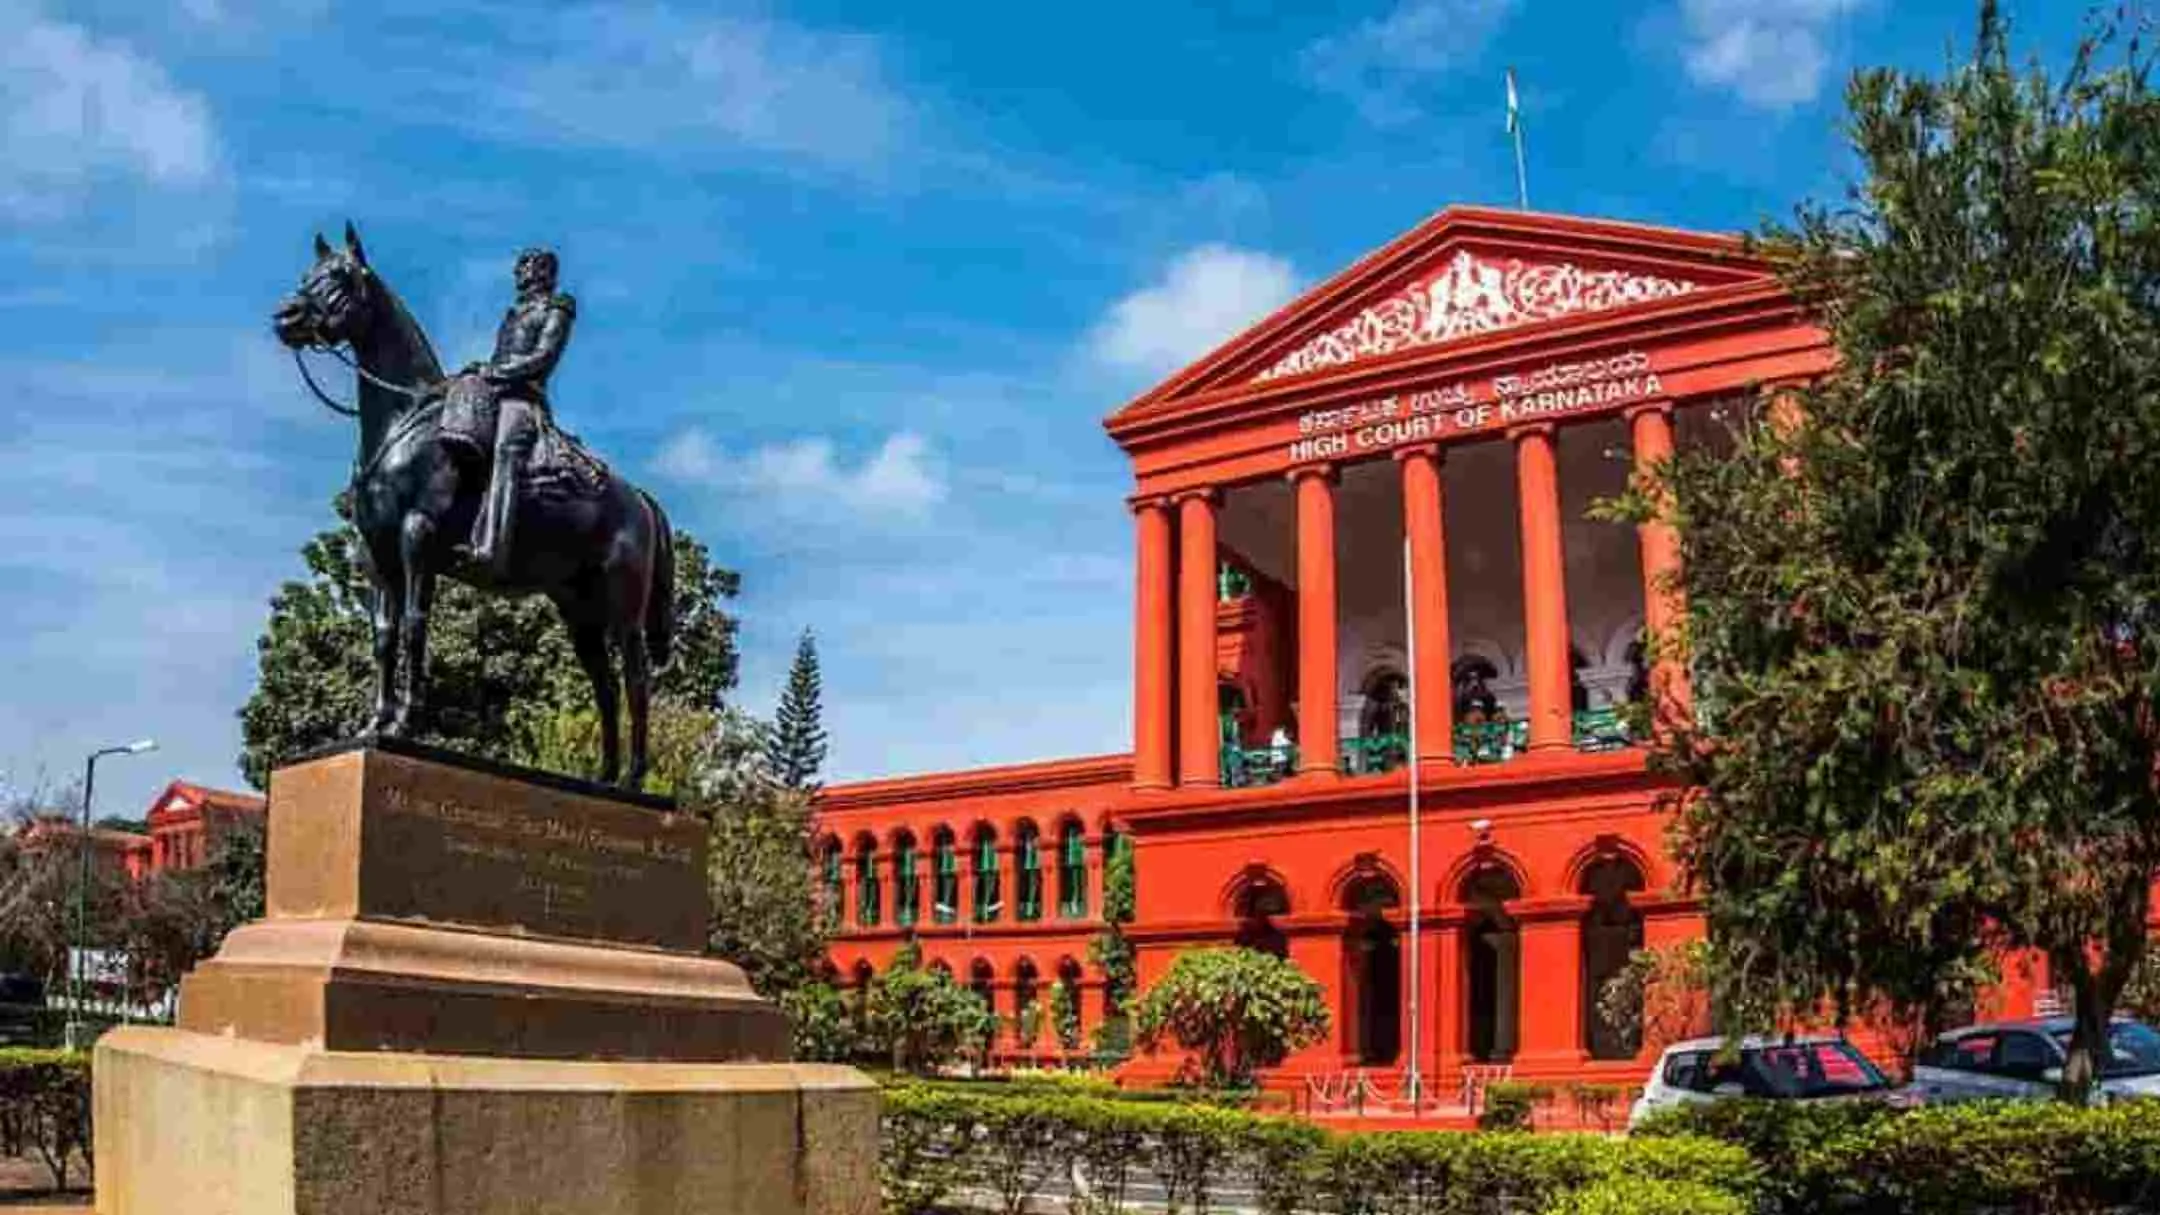
In a major victory for multinational subsidiaries operating in India, the Karnataka High Court has quashed a Rs. 57.95 crore Integrated Goods and Services Tax (IGST) demand, ruling that the secondment of foreign employees does not amount to a taxable supply of manpower services.
The bench of Justice Sachin Shankar Magadum observed that deputation arrangements fall within the employer-employee relationship exempt under Schedule III of the Central Goods and Services Tax (CGST) Act, 2017.
The case stems from a longstanding dispute between the petitioner, an Indian subsidiary of a global transport and infrastructure conglomerate, and the Karnataka GST enforcement authorities. Between July 2017 and March 2023, the company engaged technical and managerial personnel from its overseas affiliates through formal secondment agreements. These expatriates worked in India on long-term assignments, were placed on the Indian payroll, had employment contracts with the Indian entity, and were subject to Indian tax laws, including TDS deductions.
While the company viewed these secondments as part of a legitimate intra-group human resource arrangement—where the expatriates functioned as its own employees—GST authorities saw it differently. The Department alleged that the arrangement was a cross-border service transaction constituting a “manpower supply service” by the foreign entities, which should be taxed under the reverse charge mechanism (RCM) of the IGST Act.
In September 2023, the department issued a show cause notice demanding over ₹59 crore in IGST, interest, and penalties. The demand was based on the argument that the Indian entity had imported manpower services from a non-taxable territory and was liable under Notification No. 10/2017–Integrated Tax (Rate) dated 28.06.2017, which covers manpower supply services rendered from abroad.
The company asserted that the seconded personnel were under its exclusive administrative control. Salaries were paid directly by the Indian company and subjected to Indian income tax. No service fee or mark-up was charged by the foreign affiliate. From November 2020 onwards, as a matter of caution, the company had already discharged IGST on certain reimbursements under RCM and claimed Input Tax Credit (ITC).
Crucially, the petitioner relied on CBIC Circular No. 210/4/2024-GST dated 26.06.2024, which clarified that where no invoice is raised between related parties and full ITC is available, the value of service may be deemed as ‘Nil’ under Rule 28 of the CGST Rules. The petitioner argued that even if the arrangement were treated as a supply, the taxable value was ‘Nil’, making the IGST demand unsustainable.
Despite these representations, the department passed multiple orders in October 2024 confirming the demand. This led the company to approach the Karnataka High Court by way of a writ petition.
The court held that secondment arrangements where the secondee is under the control of the Indian company, is on its payroll, and performs work solely for it, reflect an employer-employee relationship and not a supply of manpower service.
The court noted that the CBIC Circular of June 2024 and GST Council’s 53rd meeting recommendations support treating such services as having ‘Nil’ taxable value when no invoice is raised and full ITC is available.
Case Details
Case Title: M/S. Alstom Transport India Limited Versus Commissioner Of Commercial Taxes
Case No.: Writ Petition No.1779 Of 2025 (T-Res)
Date: 15 July, 2025
Counsel For Petitioner: Ravi Raghavan, Smt. Meghna Lal And Smt. Vani Dwevedi
Counsel For Respondent: Jyoti M. Maradi

