
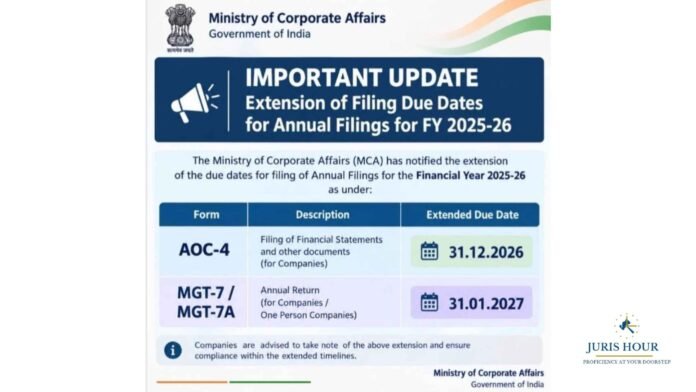
An update bearing the name and emblem of the Ministry of Corporate Affairs (MCA) states that the deadline for filing financial statements in Form AOC-4 for the financial year 2025–26 has been extended to December 31, 2026. It also states that annual returns in Forms MGT-7 and MGT-7A may be filed until January 31, 2027.
The image describes the development as an “Extension of Filing Due Dates for Annual Filings for FY 2025-26” and advises companies to complete compliance within the stated extended timelines. The dates should, however, be treated as unverified until supported by an official MCA circular or portal announcement.
Buy Now: Direct tax (Income Tax) E-Magazine September 2026
Filing Dates Mentioned In The Update
The attached image specifies the following dates:
| Form | Description in the update | Stated extended due date |
| AOC-4 | Filing of financial statements and other documents for companies | December 31, 2026 |
| MGT-7 / MGT-7A | Annual return for companies / One Person Companies | January 31, 2027 |
According to the image, the purported relaxation relates specifically to annual filings for FY 2025–26. It presents separate deadlines for financial statements and annual returns, with the annual return filing date falling one month after the financial statement filing date.
Financial Statements And Annual Returns Covered
The update identifies AOC-4 as the form for filing financial statements and other company documents. It separately identifies MGT-7 and MGT-7A as annual return forms.
If confirmed through an official notification, the additional time would allow companies and their compliance teams to organise pending documents, reconcile filing particulars and complete the relevant submissions within the notified period.
The precise scope of any relief would depend on the official notification. The screenshot alone does not establish whether the stated relaxation covers related form variants or whether any conditions apply to particular categories of companies.
No Details On Additional Fees Or Other Compliance Deadlines
The image does not specify whether the claimed extension involves a waiver of additional filing fees. It also does not explain how the purported relief would apply to filings that had already become overdue.
These details are material because a relaxation permitting filings without additional fees may differ in legal effect from a change to the underlying statutory deadline.
The screenshot also contains no statement extending the time for holding annual general meetings or completing other corporate compliance requirements. Any such relief would need to be established separately from the applicable official communication.
Official Circular Needed To Confirm Relief
Although the graphic states that the MCA “has notified” the extension, it does not reproduce or identify the underlying circular. No circular number, issue date, signatory or direct official link appears in the image.
Accordingly, the dates shown in the graphic cannot presently be reported as a confirmed regulatory extension on the strength of the attachment alone. Companies and professionals should verify the operative MCA communication before revising their compliance calendars or relying on the stated deadlines.
Read More: Delay In Filing Form 67 Can’t Defeat Foreign Tax Credit Claim: ITAT Orders Fresh Examination

