
Ask Jurishour AI

Generic selectors
Exact matches only
Search in title
Search in content
Post Type Selectors
tdb_templates
saswp_reviews
saswp-collections
saswp_rvs_location
tdc-review-email
web-story-font
web-story
googlesitekit_email
tds_locker
tds_email
saswp
mailpoet_page
mailpoet_email
tdcpt_tunes
tdc-review
pronamic_payment
pronamic_gateway
pronamic_pay_subscr
wpcode
HomeGSTRs. 12 Crore Turnover, Rs. 11,960 Discrepancy: GST Notice Sparks Call for...

Rs. 12 Crore Turnover, Rs. 11,960 Discrepancy: GST Notice Sparks Call for Rational Limits on ASMT-10 Scrutiny

Published on

🚀 Stay Connected With JurisHour

WhatsApp X Telegram

A recent ASMT-10 notice issued by the GST department has triggered concern among tax professionals, raising questions about proportionality and administrative efficiency in compliance enforcement.

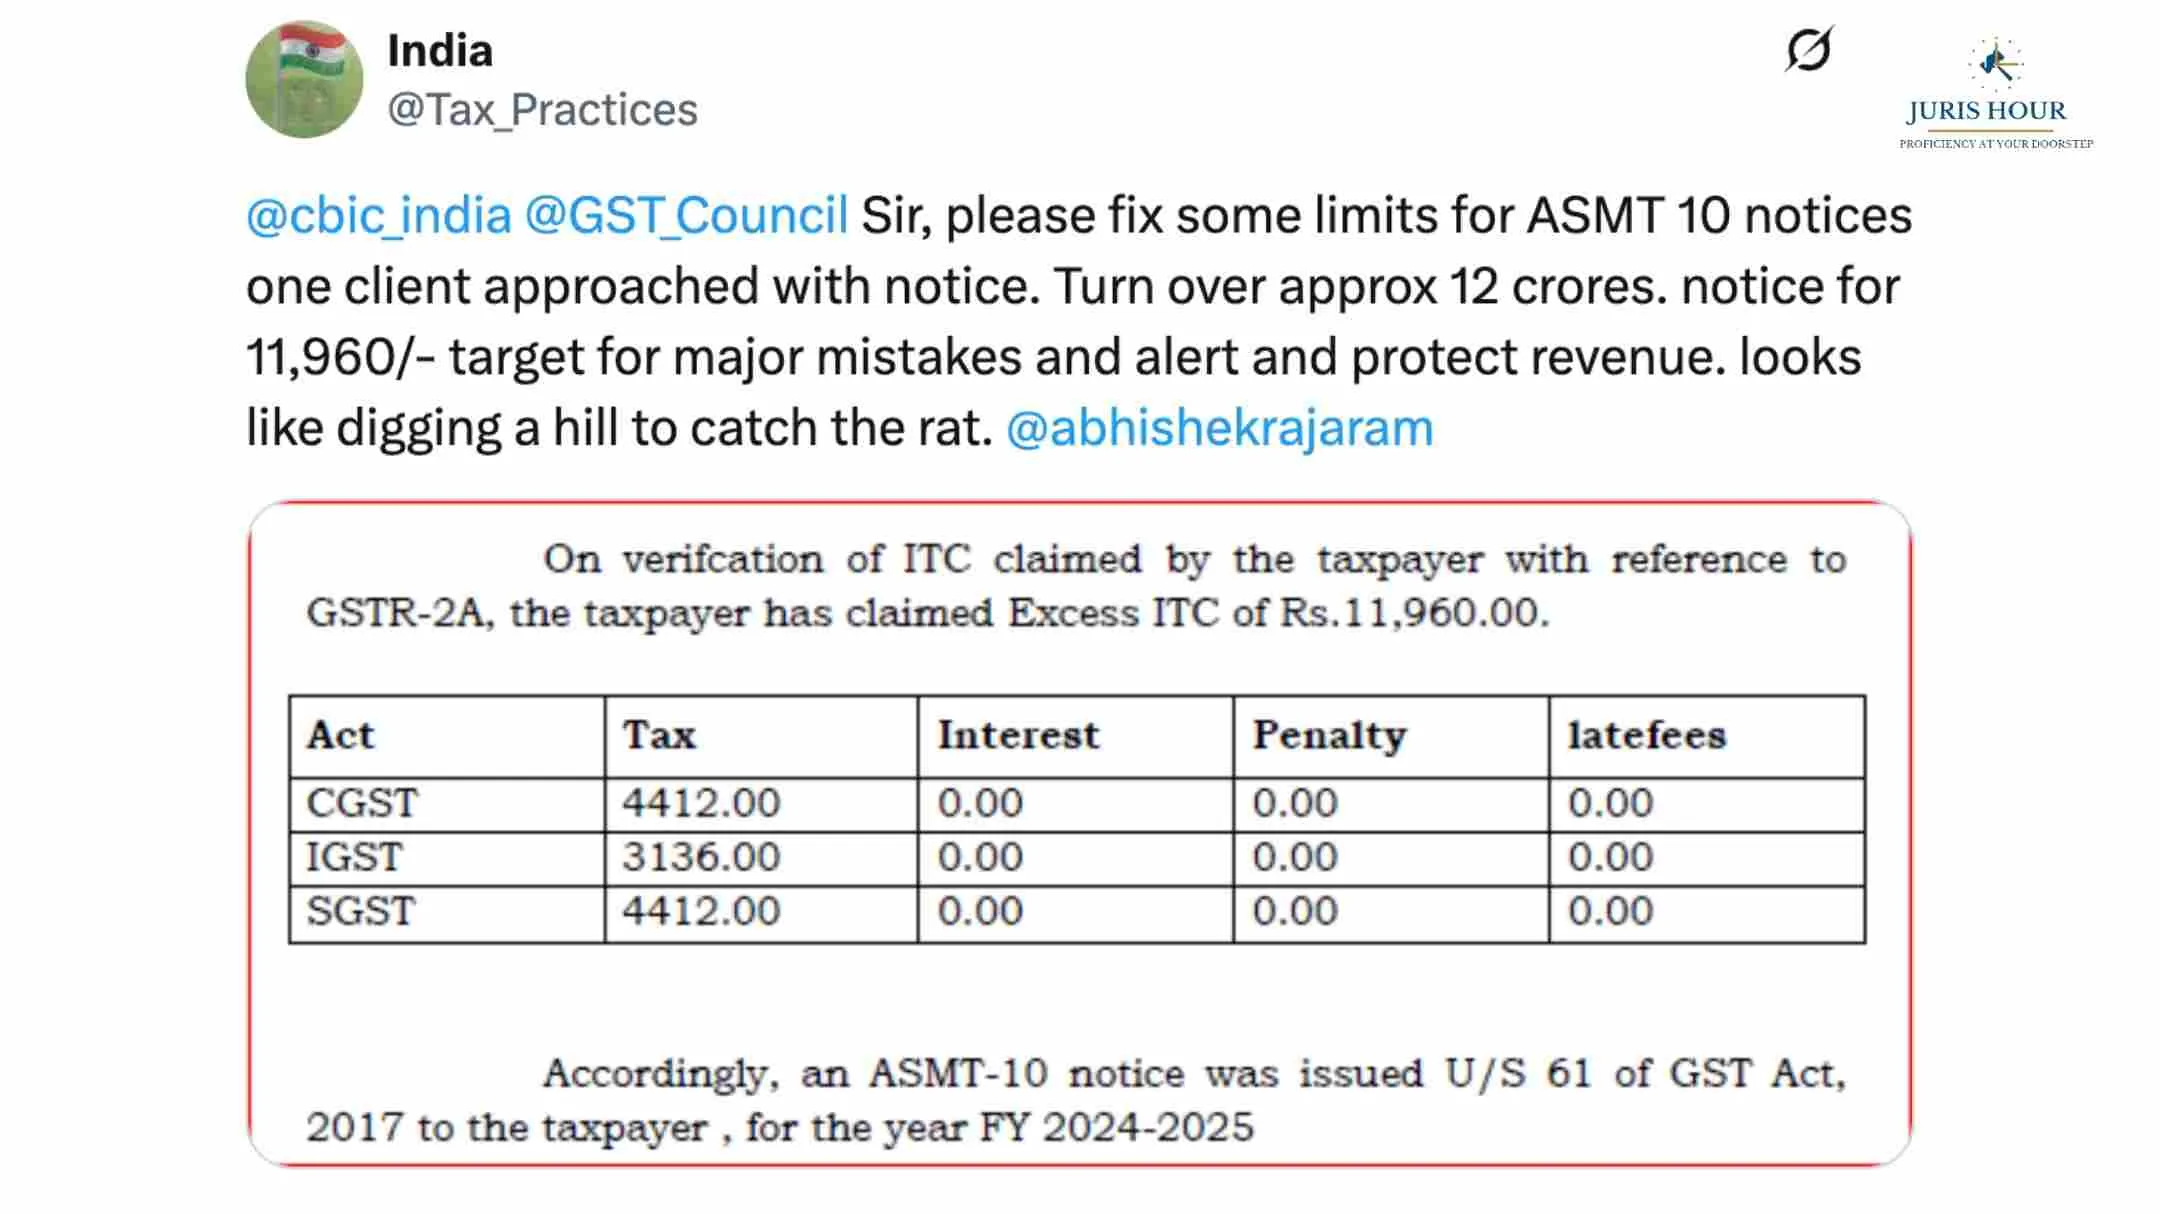
A Twitter post by a user under the handle “@Tax_Practices” highlighted the case of a taxpayer with an annual turnover of approximately ₹12 crore who was issued a notice under Section 61 of the CGST Act, 2017 for an excess Input Tax Credit (ITC) claim of just ₹11,960. The ITC in question—claimed under CGST, SGST, and IGST—was found in excess based on GSTR-2A reconciliation, but with no associated interest, penalty, or late fee.

According to the notice:

  • CGST Excess ITC: ₹4,412
  • IGST Excess ITC: ₹3,136
  • SGST Excess ITC: ₹4,412
  • Total Excess ITC: ₹11,960

Professionals argue that issuing a detailed scrutiny notice (ASMT-10) for such a small discrepancy, especially in high-turnover cases, could undermine trust and divert resources from more serious tax evasion cases. The post compared the move to “digging a hill to catch a rat,” urging the Central Board of Indirect Taxes and Customs (CBIC) and the GST Council to introduce minimum thresholds or de minimis limits for issuing scrutiny notices.

“This is not about ignoring compliance but about prioritising enforcement where it matters,” the post read, tagging senior CBIC officials and policy experts.

Call for Administrative Reform

Under Section 61, ASMT-10 notices are issued when discrepancies are noticed during the scrutiny of returns. While the provision allows officers to seek clarification on any mismatch or anomaly, tax practitioners say it needs rationalisation.

“Every small mismatch shouldn’t lead to a formal notice unless it indicates a pattern of evasion. With automation and AI now part of GSTN’s backend, alerts should be calibrated based on risk profiles,” said a senior indirect tax consultant.

Policy Implications

The incident has reignited the debate on compliance burden, especially for MSMEs and honest taxpayers. Many are urging the GST Council to:

  • Introduce monetary thresholds for issuing ASMT-10 notices.
  • Leverage data analytics to focus on high-risk cases.
  • Avoid unnecessary litigation over minor discrepancies.

As GST enters its eighth year of implementation, experts argue that fine-tuning procedural thresholds will go a long way in making the system both robust and taxpayer-friendly.

Mariya Paliwala
Mariya Paliwalahttps://www.jurishour.in/
Mariya is the Senior Editor at Juris Hour. She has 7+ years of experience on covering tax litigation stories from the Supreme Court, High Courts and various tribunals including CESTAT, ITAT, NCLAT, NCLT, etc. Mariya graduated from MLSU Law College, Udaipur (Raj.) with B.A.LL.B. and also holds an LL.M. She started her career as a freelance tax reporter in the leading online legal news companies.

Latest articles

Land Sale Taxable As Capital Gains, REIT Dividend Exempt Where SPVs Did Not Opt For Concessional Tax Regime: ITAT

The Ahmedabad Bench of the Income Tax Appellate Tribunal (ITAT) has held that income...

Share Purchase Advance Shown As Unsecured Loan Doesn’t Automatically Become Financial Debt: NCLAT

The National Company Law Appellate Tribunal (NCLAT), Principal Bench, New Delhi, has held that...

Income Tax Reassessment Based On Political Party Search Can’t Be Extended By Inapplicable Notice Procedure: ITAT

The Jaipur Bench of the Income Tax Appellate Tribunal (ITAT) has quashed a reassessment...

GST Superintendent’s Rs. 10 Lakh Jurisdiction Limit Applies to CGST Demand Alone, Not Combined CGST and SGST: Allahabad High Court

The Allahabad High Court has held that the pecuniary jurisdiction of a Central GST...

More like this

Land Sale Taxable As Capital Gains, REIT Dividend Exempt Where SPVs Did Not Opt For Concessional Tax Regime: ITAT

The Ahmedabad Bench of the Income Tax Appellate Tribunal (ITAT) has held that income...

Share Purchase Advance Shown As Unsecured Loan Doesn’t Automatically Become Financial Debt: NCLAT

The National Company Law Appellate Tribunal (NCLAT), Principal Bench, New Delhi, has held that...

Income Tax Reassessment Based On Political Party Search Can’t Be Extended By Inapplicable Notice Procedure: ITAT

The Jaipur Bench of the Income Tax Appellate Tribunal (ITAT) has quashed a reassessment...