
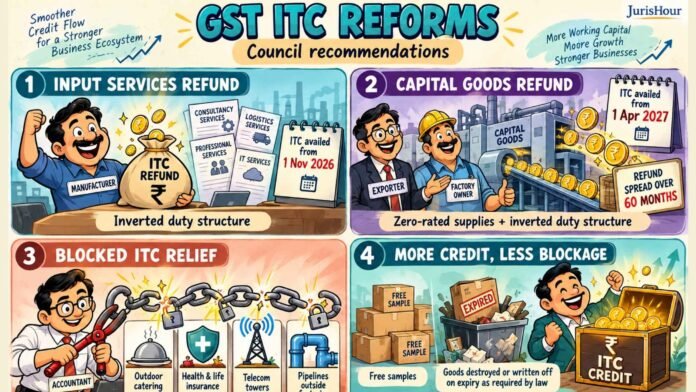
The GST Council has recommended significant changes to the input tax credit (ITC) framework, proposing refunds of accumulated credit on capital goods and input services, alongside wider eligibility for credit on several categories of business expenditure.
The recommendations seek to ease working capital constraints, reduce the cascading effect of taxes and improve the flow of credit across the supply chain. The proposed refund framework includes separate eligibility dates for input services and capital goods, with capital goods refunds to be spread over 60 months.
Buy Now: GST E-Magazine Mega Combo (11 Publications)
Refund Coverage To Expand For Exporters And Inverted Duty Businesses
The Council recommended amendments to clause (ii) of the proviso to Section 54(3) of the Central Goods and Services Tax (CGST) Act, 2017, and the CGST Rules, 2017, to expand the scope of refunds of accumulated ITC.
For refunds relating to zero-rated supplies, the proposed changes would allow refund of accumulated ITC attributable to capital goods. For refunds under the inverted duty structure, the Council recommended extending eligibility to accumulated credit on both input services and capital goods.
An inverted duty structure arises when the tax rate on inputs is higher than the rate applicable to output supplies, resulting in accumulation of credit. The proposed expansion would address the additional blockage of credit associated with services and capital investments used by eligible businesses.
Input Services Relief Proposed From November 1, 2026
The Council recommended that refunds of accumulated ITC on input services under the inverted duty structure should be available for credit availed on or after November 1, 2026.
The eligibility date is linked to when the ITC is availed. The recommendation does not provide for refund of the entire historical balance of input service credit accumulated before that date.
The proposal would widen the refund base for businesses that incur service-related expenditure while operating under an inverted duty structure, helping release credit that would otherwise remain accumulated.
Capital Goods Refunds To Be Spread Over Five Years
For capital goods, the Council recommended that refund eligibility should cover ITC availed on or after April 1, 2027, in cases involving both zero-rated supplies and inverted duty structures.
Refund of eligible capital goods credit would be spread over 60 months, or five years. The proposal therefore envisages a phased refund rather than an immediate refund of the entire eligible credit. These timelines have also been reported following the Council meeting.
The detailed calculation mechanism and procedural requirements would need to be set out in the implementing amendments and rules.
Wider ITC Eligibility For Catering, Insurance And Infrastructure
Separately, the Council recommended amendments to Section 17(5) of the CGST Act to remove restrictions on availment of ITC across several categories of supplies.
The proposed relief covers outdoor catering, health and life insurance, telecommunication towers and pipelines laid outside factory premises. It also extends to free samples and goods destroyed or written off on expiry of shelf life as required by law.
These recommendations address restrictions that can cause GST paid on business expenditure to become an embedded cost. Removing the specified blocks would enable eligible credit to flow through the tax system, subject to the general conditions for claiming ITC and the wording of the final amendments.
The proposed changes to credit eligibility and refund entitlement serve different purposes. Amendments to Section 17(5) would widen the categories on which credit may be claimed, while the refund reforms would enable specified accumulated credit to be returned to eligible taxpayers.
Legislative And Rule Changes Required
The recommendations are intended to reduce credit blockage and improve liquidity for taxpayers, particularly businesses making zero-rated supplies or operating under an inverted duty structure.
However, the Council’s recommendations do not themselves amend the CGST Act or Rules. Their implementation will require the necessary legislative amendments, rule changes and notifications. The final provisions will determine the precise scope of eligibility, refund computation and compliance requirements.
Membership Required to Access Recommendation Details & Copy
To view the complete Recommendation Details and Download Copy, you must have an active membership. Please subscribe to continue.
Read More: No GST Notices Below Rs. 10,000: GST Council Recommends Relief For Pending Cases, Lower Penalties

