
Ask Jurishour AI

Generic selectors
Exact matches only
Search in title
Search in content
Post Type Selectors
tdb_templates
saswp_reviews
saswp-collections
saswp_rvs_location
tdc-review-email
web-story-font
web-story
googlesitekit_email
tds_locker
tds_email
saswp
mailpoet_page
mailpoet_email
tdcpt_tunes
tdc-review
pronamic_payment
pronamic_gateway
pronamic_pay_subscr
wpcode
HomeColumnsTDS on Purchase of Immovable Property from Non-Residents: Clarification on Applicability of...

TDS on Purchase of Immovable Property from Non-Residents: Clarification on Applicability of TAN-Based Payment System Until September 2026

Published on

🚀 Stay Connected With JurisHour

WhatsApp X Telegram

In recent days, a significant degree of confusion has emerged among tax professionals and taxpayers regarding the procedure for depositing Tax Deducted at Source (TDS) on payments made to non-residents for the purchase of immovable property, particularly in light of the changes introduced under the Finance Act 2026 and the new Income-tax Act 2026.

The uncertainty appears to stem from a misunderstanding of the effective date of certain amendments, especially those relating to the introduction of a PAN-based TDS payment mechanism.

Existing TAN-Based System Continues Till 30.09.2026

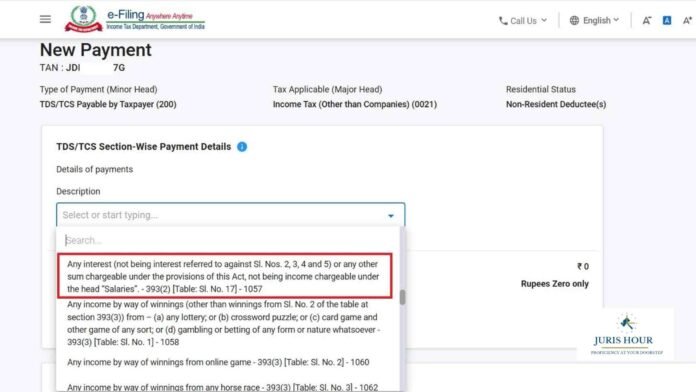
As per the current legal position, TDS payments involving non-resident deductees must continue to be made through the Tax Deduction and Collection Account Number (TAN) login. This process remains unchanged and is consistent with the procedure followed under the earlier regime.

For such transactions, the applicable section code under the new framework is Code 1057, which pertains to “interest or other sums chargeable to tax (other than salary).” Tax deductors are required to select this code while making TDS payments through the prescribed challan.

PAN-Based Payment Mechanism Yet to Come into Force

Although the Finance Act 2026 introduces a shift towards a PAN-based TDS payment system, it is crucial to note that this amendment is not immediately effective. The new mechanism will come into force only from 01 October 2026.

Accordingly, until 30 September 2026, the existing TAN-based compliance framework will continue to remain valid, and no transition to the PAN-based system is required at this stage.

Misinterpretation of Amendments Leading to Confusion

The confusion being witnessed appears to be largely due to partial reading of statutory amendments and premature assumptions that the newly introduced PAN-based mechanism has already replaced the existing system. In reality, such changes often have deferred implementation dates, allowing time for system readiness and stakeholder transition.

Advisory to Taxpayers and Professionals

Taxpayers and professionals are advised to exercise caution before acting upon unverified information, especially content circulated through social media or informal channels. It is essential to carefully examine the effective dates of legislative amendments, as announcements and enactments do not necessarily coincide with their operational commencement.

Until further notification or the notified date of implementation, the existing procedural requirements under the Income-tax law continue to govern TDS compliance in respect of non-resident transactions.

Read More: Assessee Can’t Claim Relief After Missing 3-Year Deadline: Delhi High Court Upholds Rejection of Delay Condonation Plea for Form 10-IC

Mariya Paliwala
Mariya Paliwalahttps://www.jurishour.in/
Mariya is the Senior Editor at Juris Hour. She has 7+ years of experience on covering tax litigation stories from the Supreme Court, High Courts and various tribunals including CESTAT, ITAT, NCLAT, NCLT, etc. Mariya graduated from MLSU Law College, Udaipur (Raj.) with B.A.LL.B. and also holds an LL.M. She started her career as a freelance tax reporter in the leading online legal news companies.

Latest articles

GST Demand on Money Transfer Services: Delhi High Court Sends Export and S. 74 Disputes to Appellate Authority

The Delhi High Court has directed the assessee to pursue its statutory appeal against...

GST Refund Rejection Quashed After Revised Notice Returned Undelivered: Gujarat High Court

The Gujarat High Court has set aside the rejection of a ₹3.83 lakh GST...

Customs Can’t Insist on Form-I for India–UK CETA Tariff Claims Supported by Valid Origin Declaration: CBIC

The Central Board of Indirect Taxes and Customs (CBIC) has clarified that an importer...

Can Foreign Assets Be Assessed for AY 2018–19 When the First Black Money Act Notice Was Issued in FY 2018–19? Karnataka High Court Says...

The Karnataka High Court has quashed an assessment concerning two properties in Morocco after...

More like this

GST Demand on Money Transfer Services: Delhi High Court Sends Export and S. 74 Disputes to Appellate Authority

The Delhi High Court has directed the assessee to pursue its statutory appeal against...

GST Refund Rejection Quashed After Revised Notice Returned Undelivered: Gujarat High Court

The Gujarat High Court has set aside the rejection of a ₹3.83 lakh GST...

Customs Can’t Insist on Form-I for India–UK CETA Tariff Claims Supported by Valid Origin Declaration: CBIC

The Central Board of Indirect Taxes and Customs (CBIC) has clarified that an importer...