
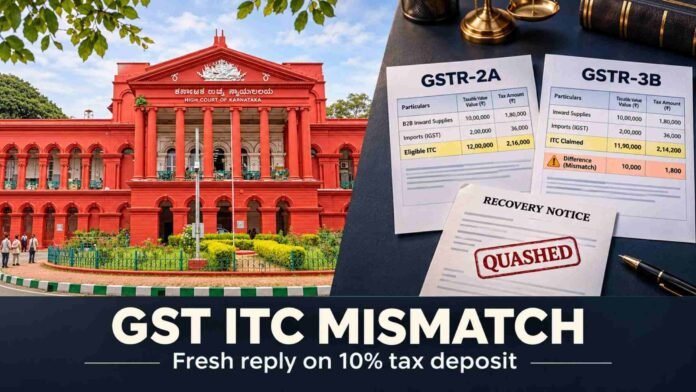
The Karnataka High Court has quashed a GST demand and a subsequent recovery notice in an input tax credit (ITC) dispute for FY 2018–19 and gave the taxpayer another opportunity to reconcile the credit it claimed in GSTR-3B with the credit reflected in GSTR-2A.
The bench of Justice B M Shyam Prasad directed the taxpayer to deposit 10% of the tax covered by the original adjudication order by 30 December 2026.
The dispute covered April 2018 to March 2019. The department passed an adjudication order under Section 73 of the CGST and Karnataka GST Acts on 30 March 2024, confirming a demand with interest and penalty over an alleged excess ITC claim in GSTR-3B compared with GSTR-2A. It subsequently issued a recovery notice in Form GST DRC-13 on 4 September 2026 under Section 79(1)(c).
Buy Now: 210+ GST Judgments E-Magazine – October 2026
The taxpayer challenged both measures and sought fresh adjudication with an opportunity to submit supplier declarations, tax invoices and reconciliation records.
Advocate Poornima H. S., appearing for the taxpayer, submitted that its representative’s health difficulties prevented it from attending the personal hearing under Section 75(4) and pursuing a statutory appeal. She told the court that the taxpayer was ready to produce documents contemplated by CBIC Circular No. 183/15/2022-GST to explain the mismatch.
Justice B. M. Shyam Prasad took into account the explanation for the taxpayer’s non-participation after filing its returns and its willingness to produce reconciliation documents. The court observed that it had granted another opportunity in similar circumstances where taxpayers had established their bona fides.
The court partly allowed the writ petition and set aside both the Section 73 adjudication order and the Section 79(1)(c) recovery notice. It permitted the taxpayer to file an additional reply and supporting documents before the Assistant Commissioner of Commercial Taxes on 30 December 2026 without waiting for a further notice.
The taxpayer must make the 10% deposit by the same date. The deposit will be subject to the outcome of the restored proceedings, in which the tax authority will determine whether the disputed credit is admissible.
Circular No. 183/15/2022-GST, dated 27 December 2022, sets out how officers should verify specified GSTR-3B and GSTR-2A discrepancies for FY 2017–18 and FY 2018–19. It covers situations such as suppliers omitting invoices from GSTR-1, reporting business supplies as consumer sales, or entering the wrong recipient GSTIN. Officers examine the invoice details and verify the applicable conditions under Section 16.
To verify payment of tax by the supplier, the circular calls for a supplier certificate when the ITC difference for that supplier in the financial year is up to ₹5 lakh. If the supplier-wise difference exceeds ₹5 lakh, it calls for a certificate from a chartered accountant or cost accountant bearing a Unique Document Identification Number (UDIN). The certificate confirms whether the supplier made the supplies and paid the tax through GSTR-3B.
Membership Required to Access Case Details & Order Copy
To view the complete Case Details and Download Order Copy, you must have an active membership. Please subscribe to continue.

