
Ask Jurishour AI

Generic selectors
Exact matches only
Search in title
Search in content
Post Type Selectors
tdb_templates
saswp_reviews
saswp-collections
saswp_rvs_location
tdc-review-email
web-story-font
web-story
googlesitekit_email
tds_locker
tds_email
saswp
mailpoet_page
mailpoet_email
tdcpt_tunes
tdc-review
pronamic_payment
pronamic_gateway
pronamic_pay_subscr
wpcode
HomeGSTGST Recovery After Tribunal Appeal: Orissa High Court Bars Further Action Until...

GST Recovery After Tribunal Appeal: Orissa High Court Bars Further Action Until Plea to Withdraw DRC-13 Is Decided

Published on

🚀 Stay Connected With JurisHour

WhatsApp X Telegram

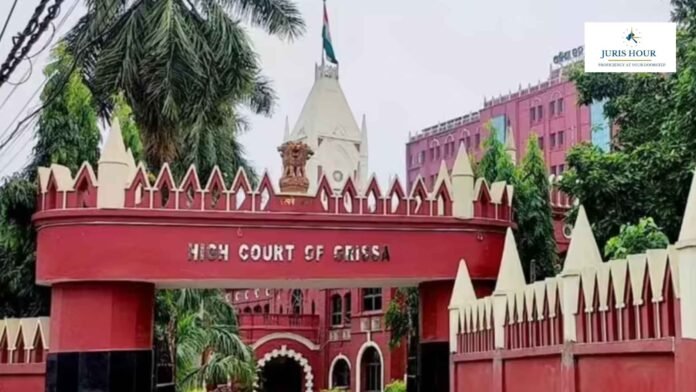
The Orissa High Court has directed the tax authorities to consider a taxpayer’s request to withdraw a GST recovery notice after he filed a second appeal before the GST Appellate Tribunal with the required pre-deposit. 

The bench of Justice Dr. Sanjeeb K. Panigrahi and Justice Murahari Sri Raman restrained further recovery until the authorities decide his applications.

BUY NOW: CCTV Safeguards in the Tax Dept. Investigations: CASE COMPILATION on Recording, Preservation and Privacy

The dispute concerned a Form GST DRC-13 notice issued on June 5, 2026, by the Joint Commissioner, CT & GST Circle, Kendrapara.

The petitioner/assessee challenged the June 5 order before the High Court. His counsel submitted that he had filed a second appeal under Section 112 of the Odisha Goods and Services Tax Act, 2017, before the GST Appellate Tribunal on June 28, 2026. According to the submission, he also deposited 10% of the disputed tax amount as the mandatory pre-deposit, and the appeal remains pending.

The taxpayer argued that the Joint Commissioner lacked the authority to issue the DRC-13 garnishee order under Section 79 of the OGST Act. He further contended that continuing recovery despite the Tribunal appeal and pre-deposit violated Section 112(9).

The taxpayer contended that he had approached the authorities to withdraw the DRC-13 notice, enclosing the Tribunal filing acknowledgement and pre-deposit challan with a letter dated September 1, 2026. The grievance, counsel said, had yet to be considered.

The High Court noted a significant point in the sequence of events: the recovery notice was issued on June 5, before the second appeal was filed on June 28. It therefore permitted Das to approach the authority concerned with an application invoking Section 112(9).

If he files that application, the authority must consider it under Section 112(9), together with the application seeking withdrawal of the DRC-13 recovery proceedings that the order records as having been filed on August 17, 2026. The Court directed the authority to pass an appropriate order in accordance with law within 15 days of September 23, 2026.

“Till disposal of the said applications, there shall not be any recovery proceeding against the Petitioner,” the Bench directed.

The Court disposed of the writ petition without deciding whether the Joint Commissioner was competent to issue DRC-13 or whether the notice must ultimately be withdrawn. Those issues remain for consideration by the authority under the Court’s directions.

Membership Required to Access Case Details & Order Copy

To view the complete Case Details and Download Order Copy, you must have an active membership. Please subscribe to continue.

Membership Required

You must be a member to access this content.

View Membership Levels

Already a member? Log in here

Read More: Service Tax Demand Sent to Bank Before Cut-Off Date Qualifies as “Quantified” Under Sabka Vishwas Scheme: Bombay High Court

Mariya Paliwala
Mariya Paliwalahttps://www.jurishour.in/
Mariya is the Senior Editor at Juris Hour. She has 7+ years of experience on covering tax litigation stories from the Supreme Court, High Courts and various tribunals including CESTAT, ITAT, NCLAT, NCLT, etc. Mariya graduated from MLSU Law College, Udaipur (Raj.) with B.A.LL.B. and also holds an LL.M. She started her career as a freelance tax reporter in the leading online legal news companies.

Latest articles

Service Tax Demand Sent to Bank Before Cut-Off Date Qualifies as “Quantified” Under Sabka Vishwas Scheme: Bombay High Court

The Bombay High Court has held a written recovery notice stating a service tax...

GST Refund Can’t Be Denied Merely Because Goods Left India After Refund Period: GSTAT

The Goods and Service Tax Appellate Tribunal (GSTAT), Chandigarh Bench has upheld an exporter’s...

Appellate Order Can’t Simply Confirm Tax Demand Without Examining Taxpayer’s Objections, Giving Reasons: GSTAT

The Raipur Bench of the Goods and Services Tax Appellate Tribunal (GSTAT) has sent...

Cash Refund Of Accumulated ITC Can Be Recovered As Erroneous Refund U/s 73 Of GST Act: GSTAT

The Goods and Service Tax Appellate Tribunal (GSTAT), has held that a cash refund...

More like this

Service Tax Demand Sent to Bank Before Cut-Off Date Qualifies as “Quantified” Under Sabka Vishwas Scheme: Bombay High Court

The Bombay High Court has held a written recovery notice stating a service tax...

GST Refund Can’t Be Denied Merely Because Goods Left India After Refund Period: GSTAT

The Goods and Service Tax Appellate Tribunal (GSTAT), Chandigarh Bench has upheld an exporter’s...

Appellate Order Can’t Simply Confirm Tax Demand Without Examining Taxpayer’s Objections, Giving Reasons: GSTAT

The Raipur Bench of the Goods and Services Tax Appellate Tribunal (GSTAT) has sent...