
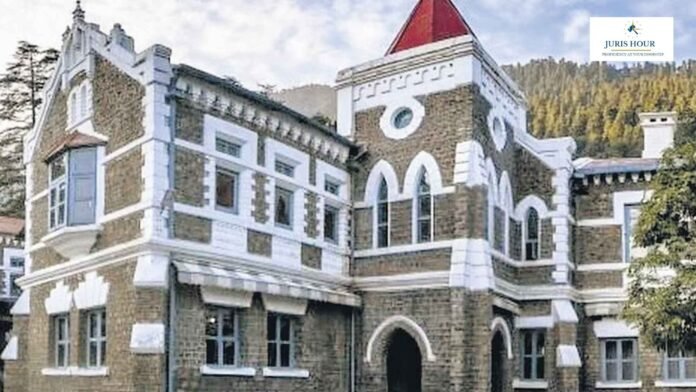
The Uttarakhand High Court has restrained GST authorities from taking any further action pursuant to a final audit report issued against a taxpayer, after a challenge was raised over the authority of the officers who conducted the audit.
The bench of Chief Justice Manoj Kumar Gupta and Justice Subhash Upadhyay passed the interim order concerning an audit conducted under the GST regime.
Buy Now: E-Handbook: Draft Replies to GST Notices On 40+ Issues
The petitioner approached the High Court challenging the issuance of Form GST ADT-01 dated June 11, 2025, through which the GST department had intimated the taxpayer that an audit was proposed to be conducted at its place of business during June 2025.
The petitioner also challenged the final audit report dated April 1, 2026, issued by the Assistant Commissioner, SGST.
The central issue raised before the Court concerned the authority of the officers who conducted the GST audit.
The petitioner relied upon a notification dated July 5, 2017, issued by the Government of India, Ministry of Finance, Department of Revenue, Central Board of Excise and Customs.
According to the petitioner’s submission, the power to conduct the audit was vested in a Deputy Commissioner or Assistant Commissioner of Central Tax. However, the audit in the present matter was conducted by a team comprising Mr. Chandresh Raj, Superintendent, and Mr. Balvinder Singh, Inspector.
The petitioner accordingly questioned whether the audit conducted by the said team was legally sustainable in view of the notification relied upon before the Court.
The Court was specifically referred to the relevant portions of the audit report contained in pages 26 and 27 of the writ petition.
Rohit Arora, the petitioner’s counsel further submitted that the controversy was not an isolated one and that an identical issue was already pending before the Uttarakhand High Court in WPMB No. 360 of 2026.
It was submitted that, in that earlier matter, the High Court had already stayed further proceedings based on the audit report.
This submission was relevant to the Court’s consideration of the request for interim protection in the present proceedings.
After hearing the submissions, the Division Bench recorded that “the matter requires consideration.”
The respondents’ counsel accepted notice on behalf of the authorities and sought three weeks’ time to file a counter-affidavit. The Court granted the requested time.
The matter has thereafter been directed to be listed along with WPMB No. 360 of 2026, where the petitioner had pointed out that an identical controversy was already under consideration.
As an interim measure, the High Court issued an important restraint against the GST authorities.
The Court directed that the respondents shall not take further action pursuant to the final audit report dated April 1, 2026, pending further consideration of the matter.
Membership Required to Access Case Details & Order Copy
To view the complete Case Details and Download Order Copy, you must have an active membership. Please subscribe to continue.

