
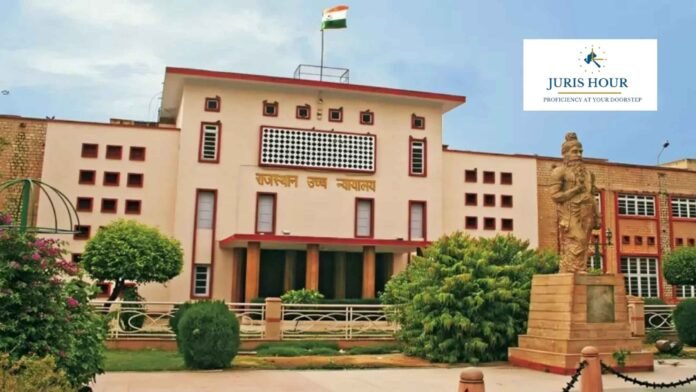
The Rajasthan High Court has directed the GST Appellate Authority to entertain an appeal against a demand of ₹36.57 lakh despite a delay of 99 days beyond the statutory limitation period, after finding that the delay arose from circumstances beyond the taxpayer’s control.
The Bench of Justice Arun Monga and Justice Ashutosh Kumar observed that a time-barred GST appeal may be considered on merits where the taxpayer establishes sufficient cause for not filing it within the period prescribed under Section 107 of the Central Goods and Services Tax Act, 2017.
Buy Now: E-Magazine: 1000+ Landmark GST Judgments (2017–2026)
The direction was issued in two connected writ petitions filed by Aakar Constructions challenging a GST demand raised for March 2023 and the subsequent seizure of its bank account.
The dispute arose from a notice dated April 27, 2023, followed by an Order-in-Original dated May 15, 2023, passed by the Deputy Commissioner, Circle-J, Jaipur-III. Through the adjudication order, the department raised a GST demand of ₹36,57,242 on the ground that the firm had not filed its GST return for March 2023.
Apart from challenging the demand notice and Order-in-Original, the firm sought the quashing of a seizure order dated August 29, 2023, along with all consequential notices and orders issued by the department.
According to the petitioner, the notice and adjudication order were not effectively served on the firm and had merely been uploaded to the GST portal. It was submitted that a dispute was continuing among the firm’s partners, due to which none of them noticed the documents uploaded online.
The petitioner claimed that it became aware of the Order-in-Original only on August 29, 2023, when its bank account was seized pursuant to the demand. After learning of the order, the firm initiated steps to comply with the statutory requirements and pursue the appellate remedy.
By that time, however, the prescribed period for filing an appeal had expired and the GST portal displayed the proposed appeal as time-barred. The firm consequently approached the High Court by filing the writ petition on December 20, 2023.
The GST authorities objected to the maintainability of the writ petition on the ground that the petitioner had not exhausted the alternative statutory remedy available under Section 107 of the CGST Act.
Section 107 permits a person aggrieved by an order or decision passed by an adjudicating authority to file an appeal before the prescribed Appellate Authority within three months from the date on which the order or decision is communicated.
The High Court accepted the department’s submission to the extent that an appellate remedy was available against the Order-in-Original dated May 15, 2023. It, therefore, declined to directly examine the merits of the GST demand without the petitioner first pursuing that remedy.
At the same time, the Bench noted that the writ petition had been instituted after a delay of 99 days beyond the statutory period available for filing an appeal. After considering the explanation placed on record, the Court found that the delay resulted from circumstances beyond the petitioner’s control.
The petitioner relied upon several earlier Division Bench decisions of the Rajasthan High Court, including M/s M R Traders v. Union of India, M/s Molana Construction Company v. Central Goods and Service Tax Department, Man Singh Tanwar v. Commissioner, Central Goods and Services Tax Department and the decisions in RPC PSIPL JV v. State of Rajasthan.
The Court noted that, in those cases, directions had been issued for time-barred GST appeals to be entertained and decided on merits where sufficient cause for the delay had been established.
Following the same approach, the High Court directed the Appellate Authority to entertain Aakar Constructions’ appeal and adjudicate it on merits, subject to the firm filing the appeal within 30 days from the date on which the High Court’s order is uploaded to its website.
The connected writ petitions were accordingly disposed of, along with all pending applications.
Membership Required to Access Case Details & Order Copy
To view the complete Case Details and Download Order Copy, you must have an active membership. Please subscribe to continue.

