
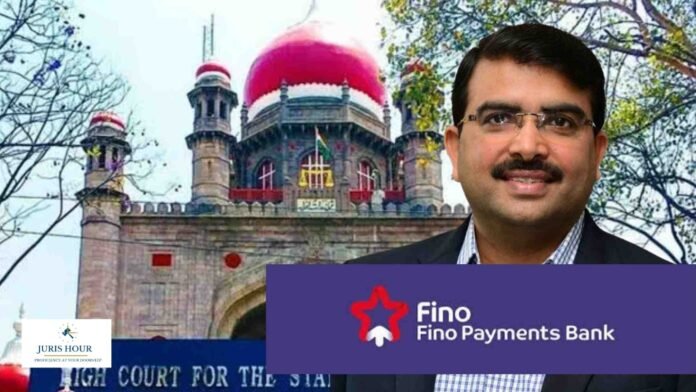
The Telangana High Court has dismissed a writ petition filed by Shri Rishi Nand Kishore Gupta, CEO of Fino Payments Bank, challenging his arrest by the Directorate General of Goods and Services Tax Intelligence (DGGI) in connection with an alleged ₹840 crore GST evasion linked to illegal online gaming operations.
The bench of Justice Aparesh Kumar Singh and Justice G.M. Mohiuddin held that the arrest was lawful, backed by sufficient material evidence, and did not violate constitutional safeguards under Articles 14, 19, 21, or 22(2) of the Constitution of India.
The petitioner, a senior banking professional and CEO of Fino Payments Bank, was arrested on February 27, 2026, under Section 132(1)(a) and 132(1)(i) of the Central Goods and Services Tax (CGST) Act, 2017. The arrest stemmed from an investigation into an alleged organized syndicate operating illegal online gaming platforms using fintech infrastructure, including payment aggregators and shell entities.
According to the DGGI, transactions worth approximately ₹3,000 crore were routed through these entities without proper invoicing, resulting in a GST evasion of about ₹840 crore.
The petitioner contended that his arrest was arbitrary, illegal, and carried out in violation of procedural safeguards. He was effectively in custody from the afternoon of February 26, 2026, when DGGI officials entered his office and restricted his movement. His production before the magistrate exceeded the constitutionally mandated 24-hour period. The allegation of “non-cooperation” was unfounded, and he had facilitated access to relevant information through his team.
The Additional Solicitor General, argued that multiple summons and notices were issued prior to the arrest, but the petitioner failed to provide required data. The arrest followed a lawful search operation and was based on “reasons to believe” supported by evidence. The petitioner gave evasive replies during interrogation and failed to cooperate with the investigation. He was formally arrested at 5:50 AM on February 27, 2026, and produced before a magistrate within 24 hours.
The High Court rejected the petitioner’s claim that he was under “custody” from February 26, holding that the presence of DGGI officers during a lawful search does not amount to arrest or custody. The arrest occurred only after the search and recording of statements concluded in the early hours of February 27. The petitioner was produced before the magistrate within the constitutionally prescribed 24-hour period.
The Court also noted that the sequence of events presented by the authorities was not effectively rebutted by the petitioner. The grounds of arrest clearly indicated involvement in a large-scale tax evasion scheme. The offences under the CGST Act were cognizable and non-bailable, justifying custodial interrogation.
The Court took note of the investigation findings, which suggested use of dummy and non-existent entities to route funds. Creation of shell companies through program managers/resellers. Failure of the bank to conduct mandatory risk audits and inspections. Alleged involvement of the petitioner as a “mastermind” in the syndicate.
It also observed that such economic offences, involving significant loss to the public exchequer, require stringent enforcement and effective investigation.
Holding that no violation of fundamental rights was established and that the arrest was supported by credible material, the High Court dismissed the writ petition.
“The petitioners have failed to make out any grounds to interfere… the arrest is lawful and within the framework of the law,” the Court concluded.
Case Details
Case Title: Shri Rishi Nand Kishore Gupta Versus UOI
Citation: JURISHOUR-492-HC-2026(TEL)
Case No.: Writ Petition No.6657 Of 2026
Date: 23.03.2026
Counsel For Petitioner: Dr. Abhishek Manu Singhvi
Counsel For Respondent: B.Narsimha Sharma
Read More: Consolidated GST SCN For Multiple FY Under Section 74 Is Impermissible: Bombay High Court

